The Spanish government aims to make it easier for people to buy their own homes and plans to launch a new financing program worth ten billion euros. A portion of this amount is to be funded through new government debt. These so-called ICO loans are primarily intended to support individuals who lack the necessary savings to purchase their first home.
Spain Expat Press Editorial Team
by Marlon Gallego Bosbach
The program is part of the Pedro Sánchez government’s new package of measures designed to ease pressure on Spain’s strained housing market. The state-backed loans are intended to enable the financing of a larger share of a property’s purchase price without buyers needing to have substantial personal savings upfront.
Up to 50,000 euros in addition to the mortgage
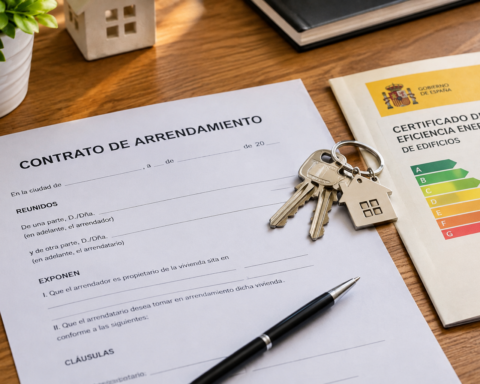
Through the program, buyers can obtain a loan of up to 20 percent of the purchase price. The maximum amount is 50,000 euros. The loan carries zero percent interest, and no commissions are charged.
The scheme is aimed at people who would generally qualify for a mortgage but struggle to raise the down payment usually required. In Spain, banks typically finance only a portion of the property price; state funding is intended to bridge this gap, at least in part.
For an apartment valued at 200,000 euros, for example, around 40,000 euros could be covered by the state loan. With a purchase price of 250,000 euros, up to 50,000 euros would be possible. However, buyers must still cover the additional costs associated with the property purchase – such as taxes, notary fees, and registration fees – themselves.
Repayment only after the mortgage
The planned repayment structure is particularly unusual. While the regular bank mortgage is running, a repayment holiday may apply to the ICO loan; this can last for up to 30 years. Repayment of the state loan begins only after the standard mortgage has been paid off, with up to ten years available for this subsequent phase.
With this move, the government is opting for a long-term financing mechanism. The ten billion euros are not intended for a one-off expenditure; as borrowers repay their state-backed loans, the funds can be redeployed for other buyers.
Part of the money comes from new debt
To finance the program, the Spanish state is resorting to new borrowing, among other measures. A portion of the ten billion euros is to be raised through issuances by the Spanish Treasury. In addition, existing, previously unused state funds are being utilized.
In doing so, the state deliberately incurs new debt to facilitate access to the housing market. However, the government views the model as a revolving fund: the funds deployed are intended to flow back into the system over the long term through borrower repayments and subsequently become available again for other first-time buyers.
Not exclusively support for young people
Although young people are among the key target groups, the program is not restricted exclusively to a specific age group. There is no general age limit. The decisive factor is, rather, that the purchase involves one’s first own home and that the other program requirements are met.
At the same time, the government aims to prevent state support from being used for speculation. Consequently, restrictions regarding future sale and potential renting out apply to the subsidized properties.
Sales and rentals are being restricted
Anyone wishing to resell a home financed through the program should not be free to set the price entirely at their own discretion. In principle, the original purchase price is to remain the benchmark, though it may be adjusted for inflation under certain conditions. Certain investments made in the property may also be taken into account.
Restrictions also apply to renting out the property. The rent must not exceed the government-set reference limits. Furthermore, the relevant conditions are to be recorded in the property’s notarial documentation.
With this measure, the government aims to prevent buyers from benefiting from state support initially and subsequently reselling the property at a high profit or renting it out at exceptionally high prices.
Concrete implementation is still pending
Despite the approved financing framework, interested parties cannot simply apply for the new loans immediately. Further details still need to be determined for practical implementation. These include, among other things, specific eligibility criteria and the final price limits for properties eligible for financing under the program.
The ten billion euros thus serve, for the time being, as the financial framework for a long-term instrument. With this measure, the government aims in particular to pave the way to home ownership for those who have sufficient income for a mortgage but lack the necessary savings for the required down payment.
The new program is also another attempt by the government to reduce pressure on the Spanish housing market. In addition to purchase support, Sánchez is focusing on expanding the supply of affordable housing and implementing further measures to limit housing costs.