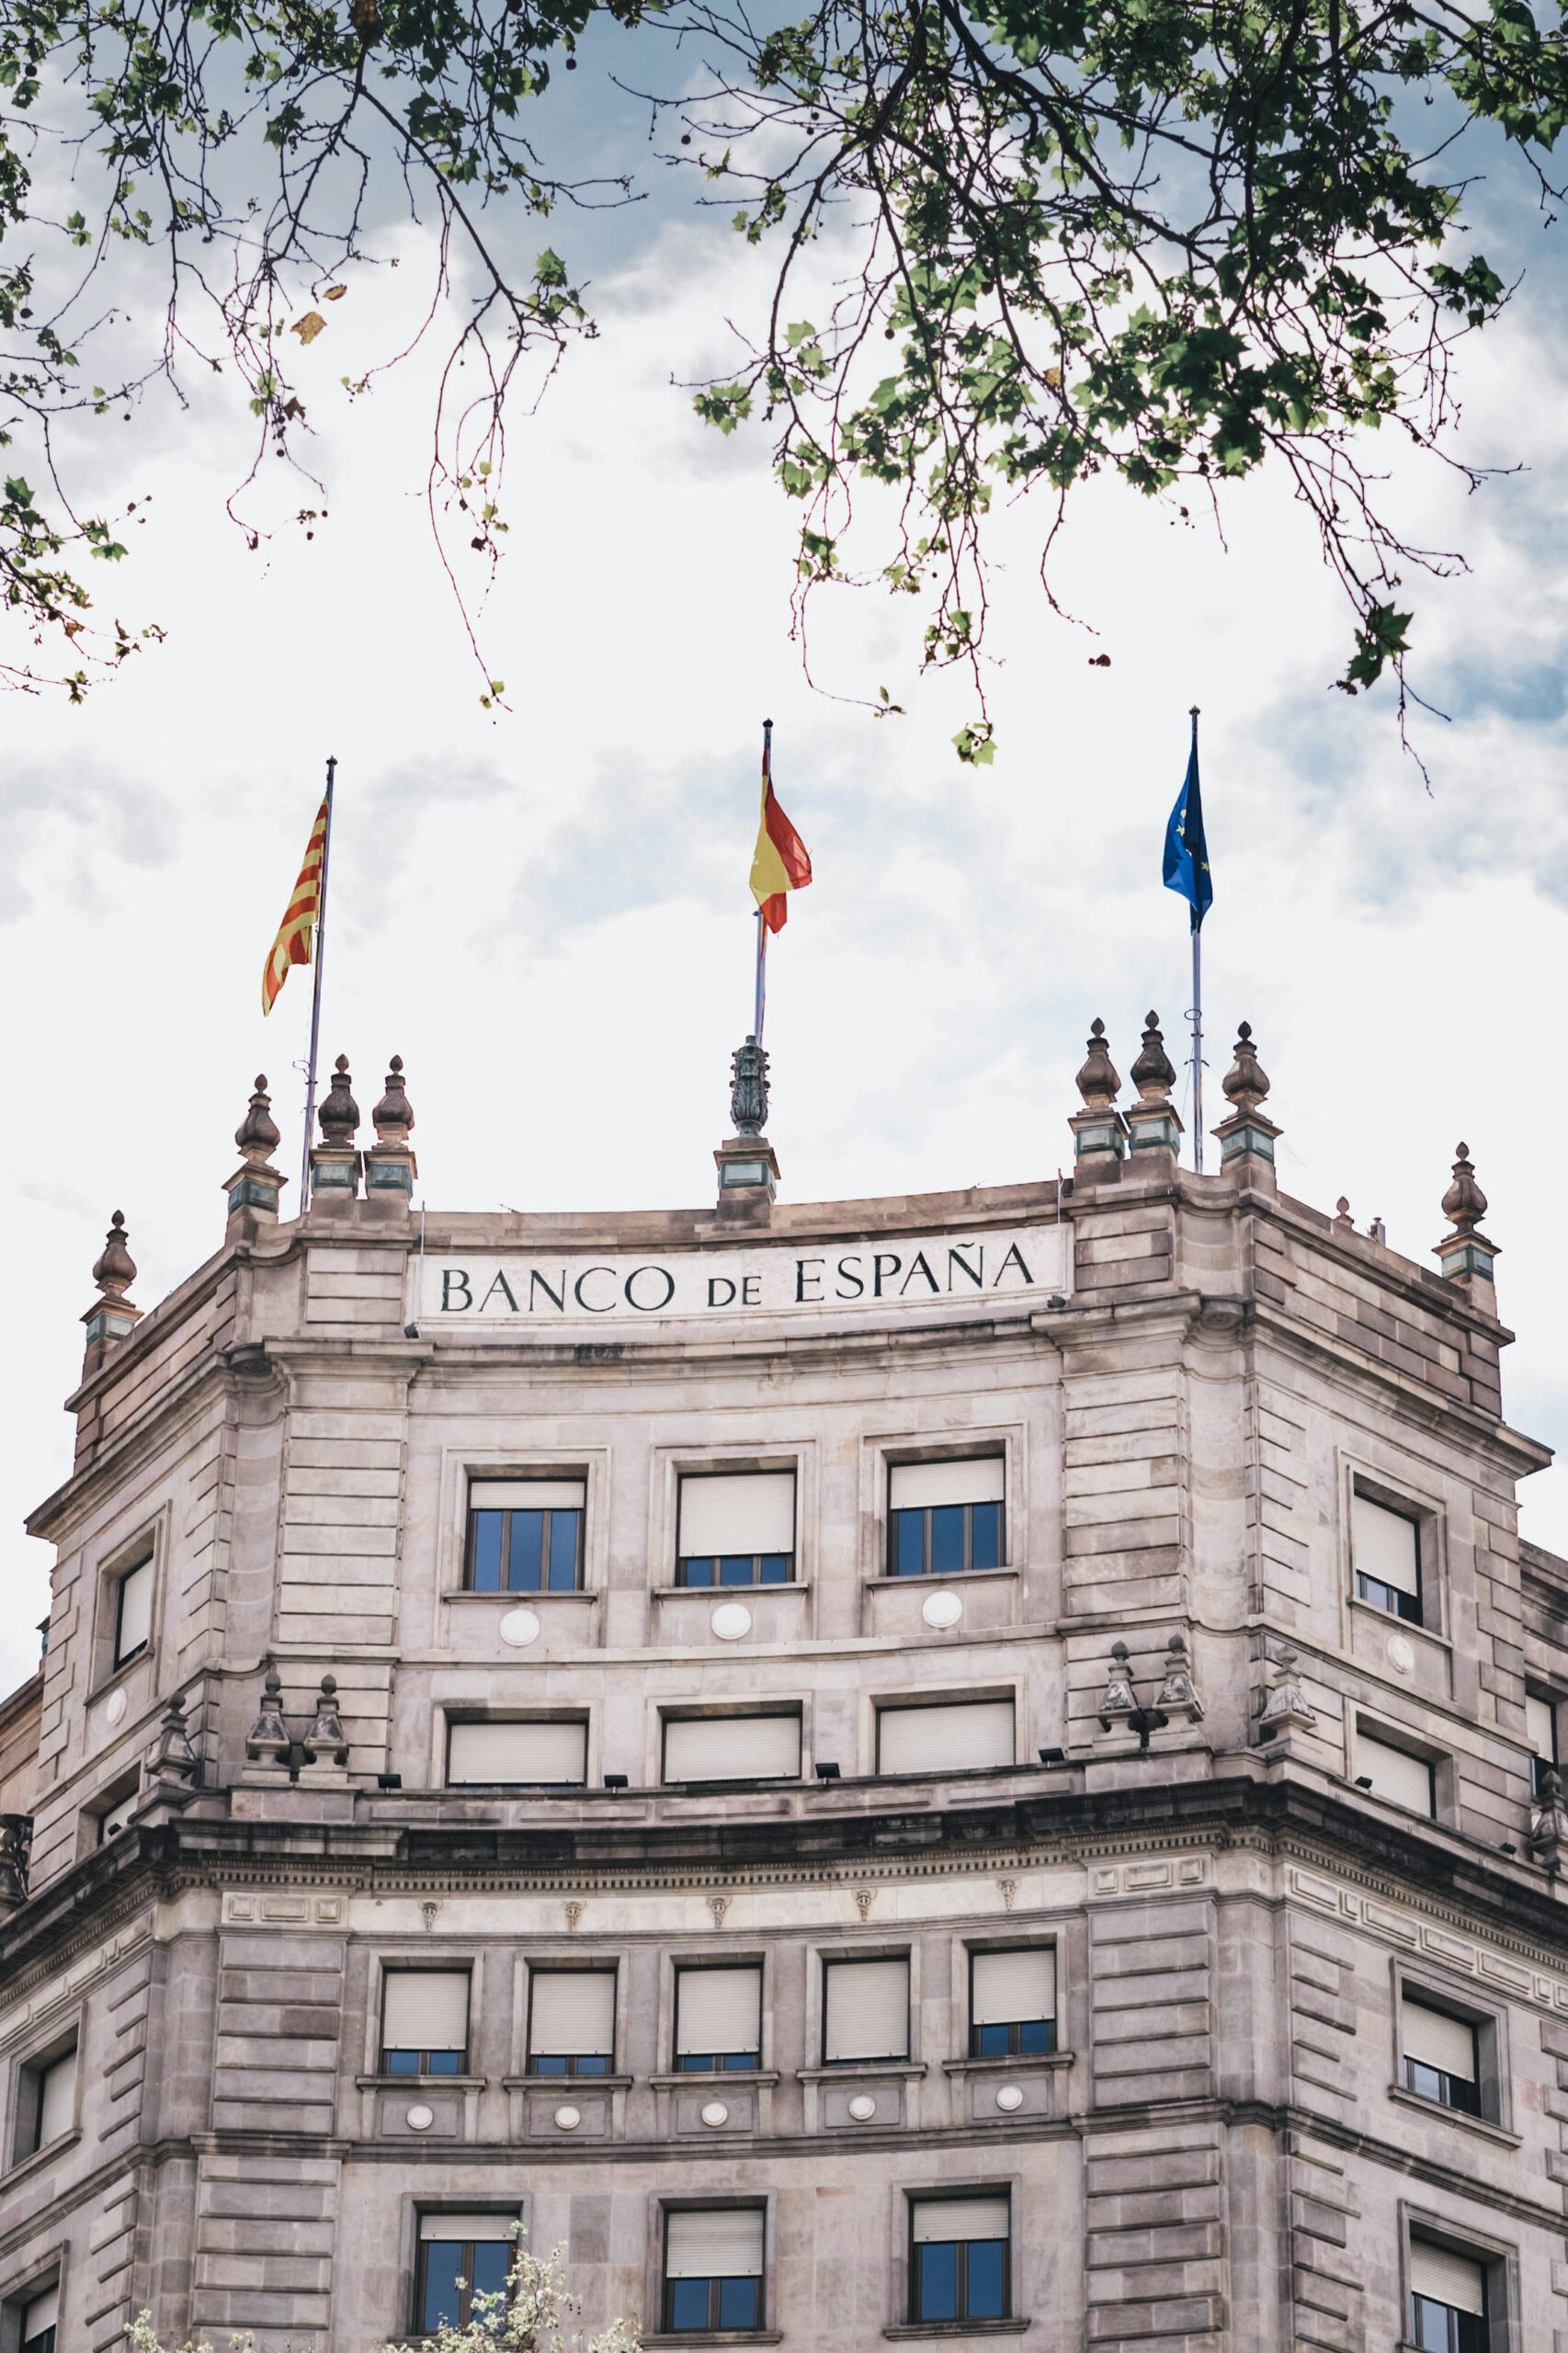
Despite rising property prices and ongoing tensions in the Spanish housing market, the Spanish central bank does not currently foresee a new property crisis. In a recent assessment, it is emphasised that the market is structurally very different from the situation ahead of the 2008 financial crisis.
Spain Expat Press Editorial Team
by Marlon Gallego Bosbach
Market shows stability rather than overheating
At the centre of the analysis is the assessment that current price developments are not comparable to the property boom of the time. While the market around two decades ago was strongly driven by speculative investment and generous lending, the current trend, according to the Spanish central bank, is primarily based on genuine demand and a limited supply of housing.
Although property prices have risen noticeably in recent years, they still remain below the peak levels reached before the financial crisis.
Significantly stricter lending standards than in the past
A key difference compared with the market environment at the time lies in the way financing is structured. Banks now grant mortgages far more cautiously and under stricter conditions than in the period before 2008. Back then, very high loan-to-value ratios, and even loans exceeding the actual property value, were not uncommon, whereas today more conservative financing models dominate.
According to the Spanish central bank, this development is a key factor in why the risk of systemic overheating is currently considered low.
Demand is driving the market – not speculation
The current market dynamics are primarily supported by structural factors. These include continued population growth, immigration from abroad, and particularly strong demand in urban and tourist regions. In addition, a significant shortage of new housing is further restricting the available supply.
Unlike in the period before the financial crisis, speculative excesses now play only a minor role.
Housing market remains under pressure
Despite the overall stable assessment, the housing market situation remains tense. In many parts of the country, both purchase prices and rents continue to rise, while access to affordable housing is becoming increasingly difficult. Young people and households with medium and lower incomes are particularly affected.
The Spanish central bank sees the main cause of this as the ongoing shortage of supply, which is unable to keep pace with demand.
Growing political pressure to act
Against this backdrop, pressure on policymakers is increasing. The Spanish central bank points out that closer coordination between national, regional and municipal authorities is necessary in order to effectively promote housing construction.
The central question is how the supply of housing can be sustainably increased in order to ease existing market tensions in the long term.
Lending is growing moderately
Mortgage lending in Spain is also increasing slightly again, but remains overall within a controlled framework. Household private debt continues to stand at a moderate level, especially compared with the situation before 2008. An excessive credit expansion, as seen at that time, is currently not evident.
Stable market with a structural issue
The assessment by the Spanish central bank paints an overall picture of a stable yet simultaneously strained property market. There are currently no indications of an impending property bubble or an imminent crash.
At the same time, the structural problem of housing shortages persists, placing continued upward pressure on prices in many regions of the country and significantly shaping the long-term development of the market.